Detail Side-by-side Vehicle Purchase Pricing And Standard Financing Options
So, there I was, standing in the bustling car showroom, my heart set on the shiny new SUV that had been winking at me from the lot. I'd saved up, done my research, and was rea...

So, there I was, standing in the bustling car showroom, my heart set on the shiny new SUV that had been winking at me from the lot. I'd saved up, done my research, and was ready to take the plunge. But as I sat down with the salesperson, I realized I'd forgotten one crucial detail - how much was this baby going to cost me, really?
That's when I learned about the magic of side-by-side vehicle pricing and standard financing options. It's like when you order a pizza - you think you're getting a simple cheese, but then they hit you with the 'plus $2 for extra toppings' and 'add $3 for delivery' fees. Suddenly, you're not just looking at a $10 pizza anymore, are you?
Side-by-Side Pricing: The Good, The Bad, and The Ugly
Alright, let's dive into the good first. Side-by-side pricing, as the name suggests, is when the dealer gives you two prices side by side - the Manufacturer's Suggested Retail Price (MSRP) and the dealer's price. It's like they're saying, "Here's what the car company thinks you should pay, and here's what we think you should pay." Isn't that sweet of them?
Must Read
Now, the bad. The MSRP is just that - a suggestion. It's not set in stone, and it's often higher than what the dealer actually wants for the car. So, when you see that side-by-side pricing, remember that the MSRP is just a starting point for negotiations. It's like when your mom says, "I think you should clean your room," but you know she'd be happy if you just picked up your socks.
The ugly? Some dealers might use side-by-side pricing to make you think you're getting a great deal when you're not. For instance, they might inflate the MSRP to make their price seem lower. So, always do your own research and know the market value of the car before you start negotiating.
Financing Options: The Mystery of the Monthly Payment
Now, let's talk about financing. You've probably seen those ads - "Buy this car for just $X a month!" It sounds amazing, right? But here's the thing, that monthly payment is just one piece of the puzzle.
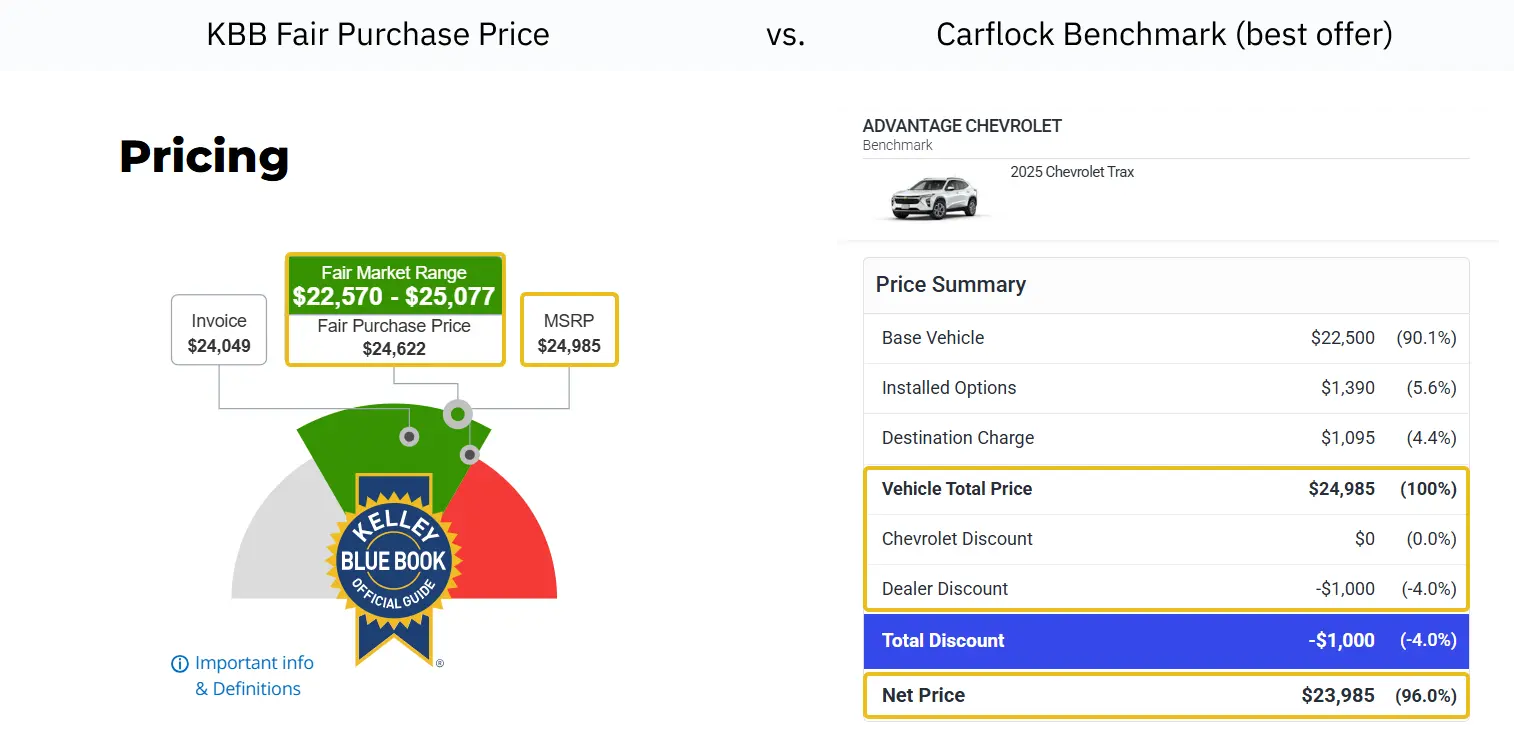 Analyzing Kelley Blue Book Fair Purchase Price
First, there's the interest rate. This is the percentage the lender charges you for borrowing the money. It's like when you borrow $20 from your friend and they say, "No problem, just pay me back $25 next week." The extra $5 is the interest.
Then there's the term - how long you'll be paying back the loan. A shorter term means higher monthly payments but less interest overall. A longer term is the opposite. It's like choosing between paying off your credit card in one go (ouch) or spreading it out over a few months (easier, but you'll pay more in the long run).
And don't forget the down payment. This is the amount you pay upfront to lower the total amount you need to finance. It's like when you order a pizza and they say, "That'll be $20," but you hand them $10 and say, "Keep the change." The more you pay upfront, the less you'll pay in the long run.
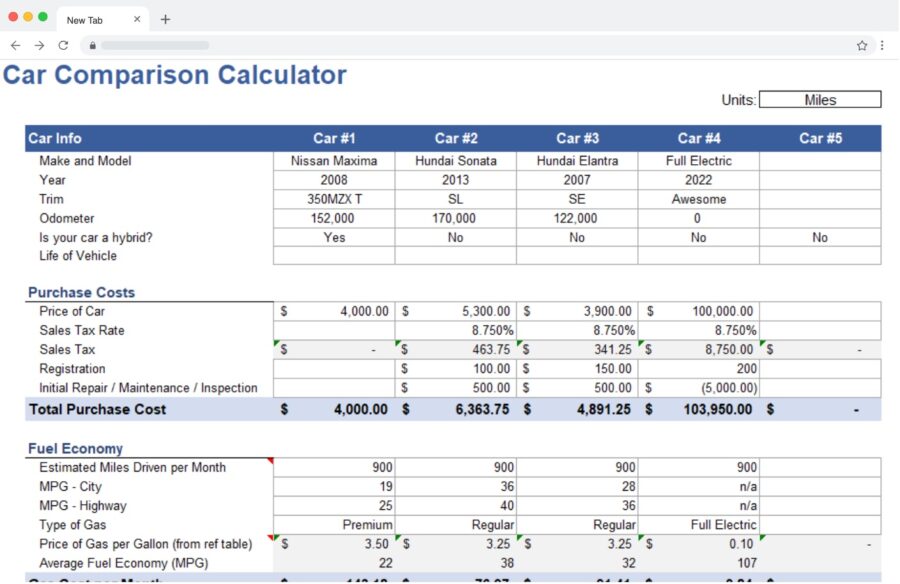 7 Free Car Comparison Spreadsheets For Buying Your Next Car-Tiller
Putting It All Together
So, back to my SUV. After some negotiating and crunching some numbers, I found out that the car I wanted was going to cost me more than I thought. But I also found out that I could afford it if I played my cards right. I got a good deal on the price, a reasonable interest rate, and a term that worked for me. And I even managed to negotiate a better down payment.
My advice? Don't just focus on the monthly payment when you're buying a car. Look at the whole picture - the price, the interest rate, the term, and the down payment. And always, always do your research. Knowledge is power, my friends, and in the car-buying world, that power can save you a lot of money.
Now, if you'll excuse me, I've got a shiny new SUV to break in. And yes, I'll be careful with the pizza grease. Happy car shopping!
