Current Mortgage Interest Rates Switzerland 2026
So, you’re thinking about buying a little slice of Swiss paradise—a chalet with a view of the Matterhorn, a cozy apartment in Zürich, or maybe a farmhouse where you can finall...

So, you’re thinking about buying a little slice of Swiss paradise—a chalet with a view of the Matterhorn, a cozy apartment in Zürich, or maybe a farmhouse where you can finally keep those goats you’ve been dreaming about. But then reality hits: mortgage rates. Cue the dramatic sigh. Don’t worry, friend. Grab a coffee (or a fondue, I won’t judge), and let’s chat about what’s happening with current mortgage interest rates in Switzerland for 2026—because, yes, we’re already there, and the news is actually pretty good.
First, the big picture. After a few years of the Swiss National Bank playing whack-a-mole with inflation (remember when we all panicked about the price of Gruyère?), things have finally settled down. As of early 2026, the SNB has kept its key policy rate hovering around 1.0% to 1.25%. That’s a cozy spot—not too hot, not too cold, like Goldilocks’ porridge. For you, this means mortgage rates have dropped a solid 0.5% to 0.75% from their 2023 peak. Yes, you read that right: dropped. The era of panic-refinancing is officially over. Take a victory lap—just don’t trip over the cowbells.
Let’s talk numbers, because you’re Swiss and you love precision (and so do I). For a standard fixed-rate mortgage, you’re looking at about 1.8% to 2.3% for a 10-year term. If you’re feeling adventurous, a Saron mortgage (the floating-rate darling) is sitting around 1.4% to 1.7%. That’s basically the financial equivalent of finding a parking spot in Bern on a Saturday. Pro tip: Lock in a fixed rate if you value sleep. Opt for Saron if you like living on the edge—and checking rates every morning with your espresso. But honestly? Either way, you’re winning compared to your neighbors in the Eurozone or the US, who are still staring at 4% rates while weeping into their croissants.
Must Read
Now, the secret sauce in Switzerland is your loan-to-value ratio. Banks are still picky—they’re Swiss, after all—but they’re in a friendly mood. You’ll need at least 20% down payment (sorry, no magic wand for that), and your total housing costs shouldn’t exceed 33% of your gross income. Amortization? Yes, you must pay it down to 66.67% within 15 years, or 20 years for older homes. Think of it as a forced savings plan—except you can’t blow it on a weekend in St. Moritz. First-time buyers, listen up: you can now use pillar 2 pension funds for that down payment. Just don’t tell your future retired self, okay? They’ll understand. Probably.
What about the regional quirks? Oh, Switzerland never disappoints. In Zürich and Geneva, rates are slightly higher (about 0.1% to 0.2%) because everyone wants to live there—it’s the real estate equivalent of a hot ticket. In rural Valais or Jura, you’ll get a slight discount for the privilege of hearing cows moo instead of trams screech. My advice? If you can handle the commute, buy where the edelweiss grows. Your wallet will thank you, and your stress levels will drop faster than a Toblerone at a ski lodge.
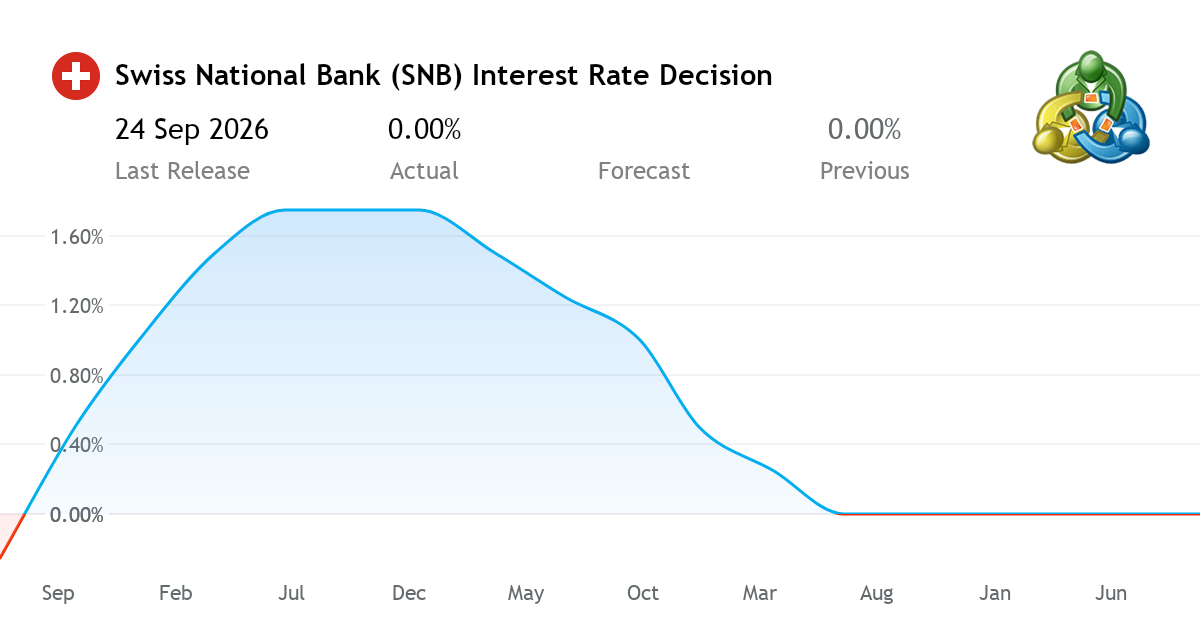 SNB Interest Rate Decision 2026 - economic indicator from Switzerland
Here’s the uplifting part: analysts predict rates will stay stable through the rest of 2026. No spikes, no drama—just a gentle, predictable path. The Swiss economy is humming along (chocolate exports are up, obviously), and the SNB has declared that inflation is officially tamed. So, now is a genuinely good time to buy, refinance, or even sneak in that second home for Alpine escape. Yes, even with the quirky rules, the high down payment, and the occasional banker who looks at you like you just asked to borrow their fondue set.
So go ahead. Call your mortgage advisor, browse those lake-view listings, and start dreaming of your future life where your biggest worry is whether to buy a fondue set or fondue pot (spoiler: get the pot, it’s classier). The rates are friendly, the SNB is chill, and Switzerland is still the most beautiful place to overpay for a loaf of bread. You’ve got this. And hey, if all else fails, just remember: a mortgage is just a fancy way of saying “I love this view so much I’ll pay for it for the next 20 years.” Worth it.
