Can Being A Cosigner Affect Your Credit
Being a cosigner for a loan, credit card, or rental agreement is one of the most helpful things you can do for someone in need. Whether you're helping a young relative secure...
Being a cosigner for a loan, credit card, or rental agreement is one of the most helpful things you can do for someone in need. Whether you're helping a young relative secure their first car or supporting a friend who needs a little boost, cosigning has become an incredibly popular and useful practice. But there's an important question that many people overlook: can being a cosigner actually affect your own credit? The short answer is yes — and understanding how is crucial before you sign on the dotted line.
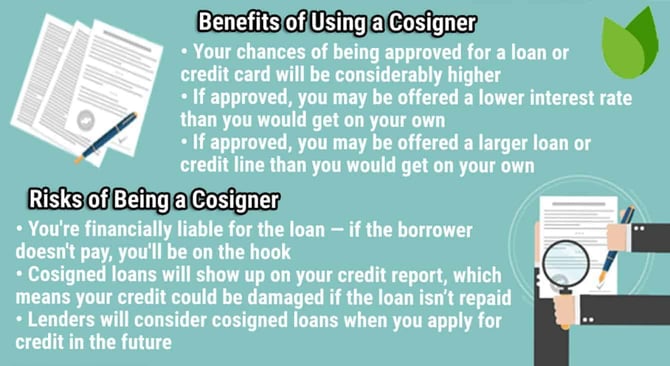
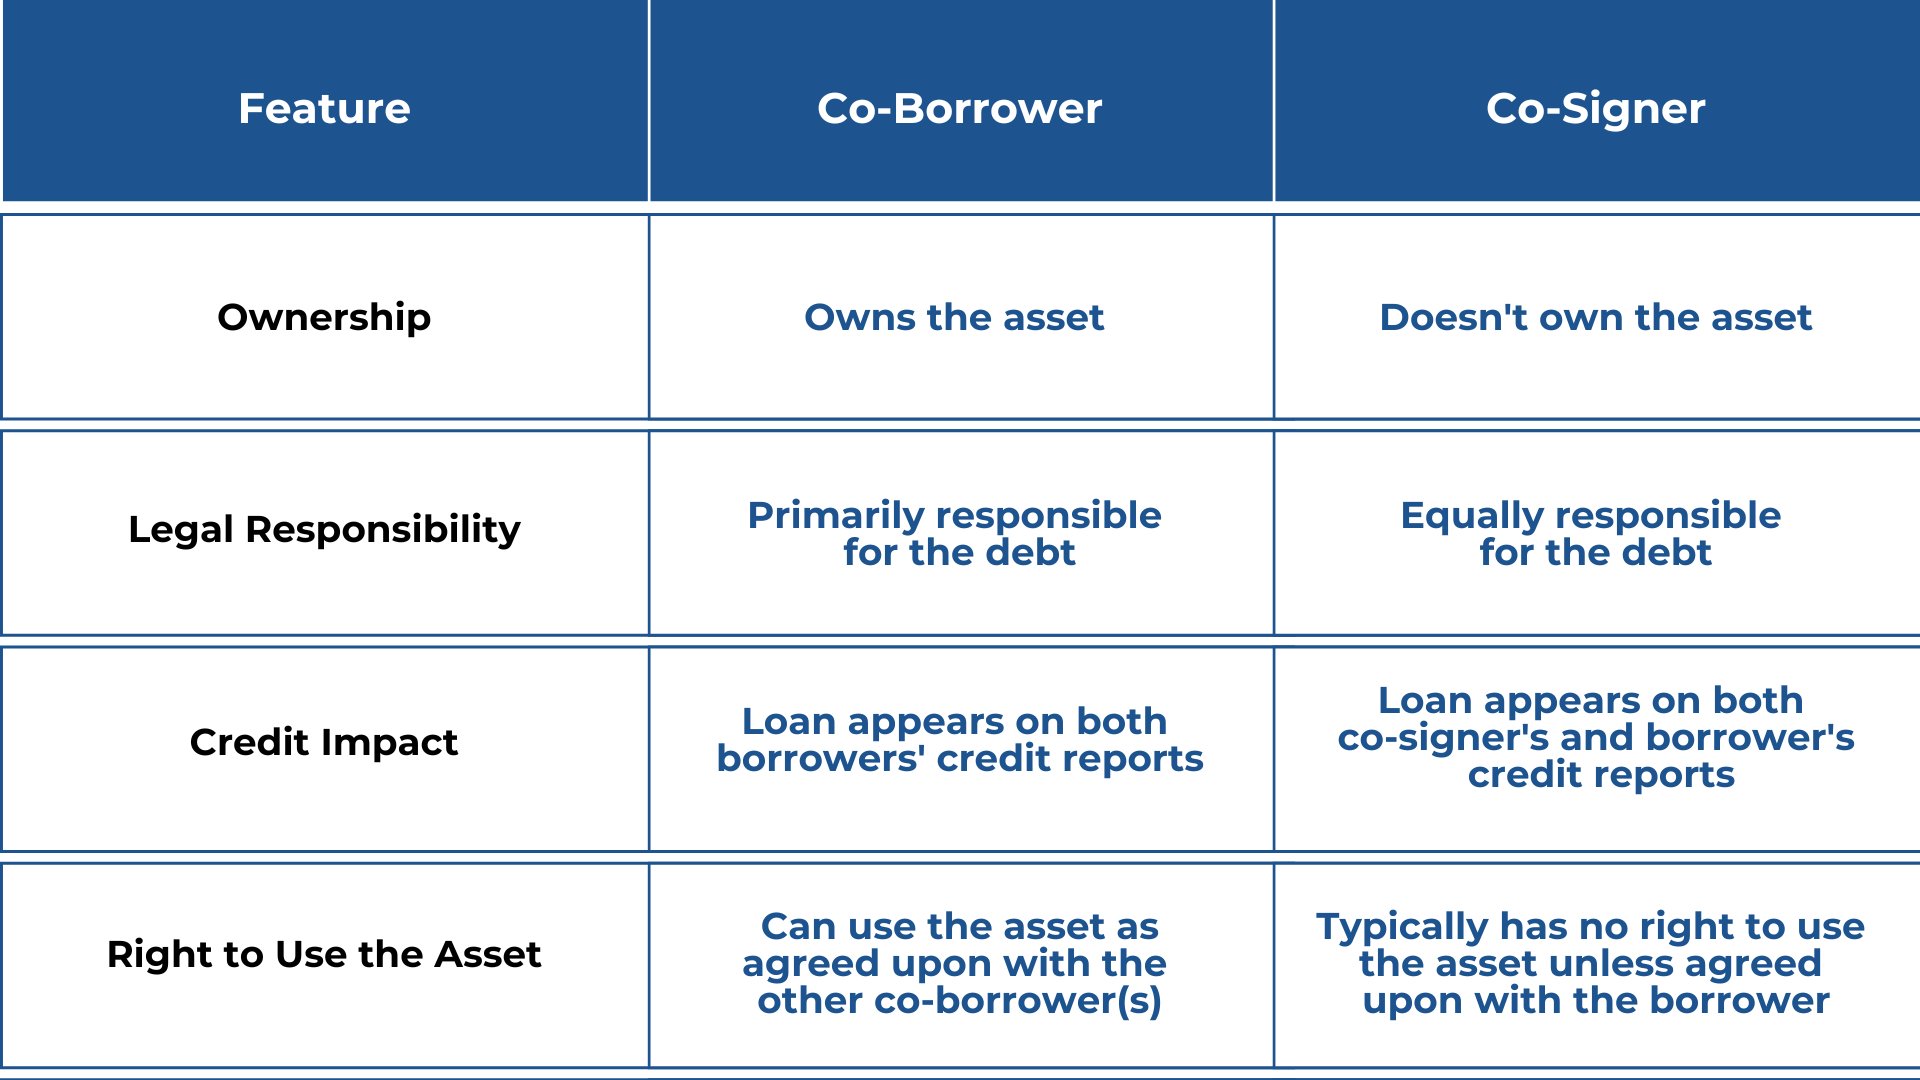
When you agree to become a cosigner, you are essentially placing your creditworthiness on the line alongside the primary borrower's payment history. This matters because any missed or late payments made by the borrower will be reported on your credit report as well. Lenders see you as equally responsible for the debt, which means your credit score can drop just as fast as theirs if things go sideways. On the flip side, if the borrower makes every payment on time, it can actually help build a positive credit history for you over time.
There are also hidden impacts that many cosigners never anticipate. For instance, the loan amount adds to your total debt-to-income ratio, which lenders evaluate when you apply for your own mortgage or car loan. This means that even if you've never missed a payment, having a cosigned loan on your record could make it harder for you to qualify for future credit. Additionally, if the borrower defaults completely, you become the sole person responsible for repaying the full balance — a situation that has left many families in financial hardship.
Must Read
Real-life examples help illustrate the gravity of this commitment. Consider a parent who cosigns a student loan for their teenager. For years, everything goes smoothly, and both parties benefit. However, after graduation, the student faces unemployment and misses several payments. The parent's credit score suddenly takes a significant hit, and their mortgage refinancing gets denied. Another example is a young professional who agreed to cosign an apartment lease for a roommate. When the roommate vacates and leaves unpaid rent behind, the cosigner's credit suffers, making it difficult to rent a new place in another city.
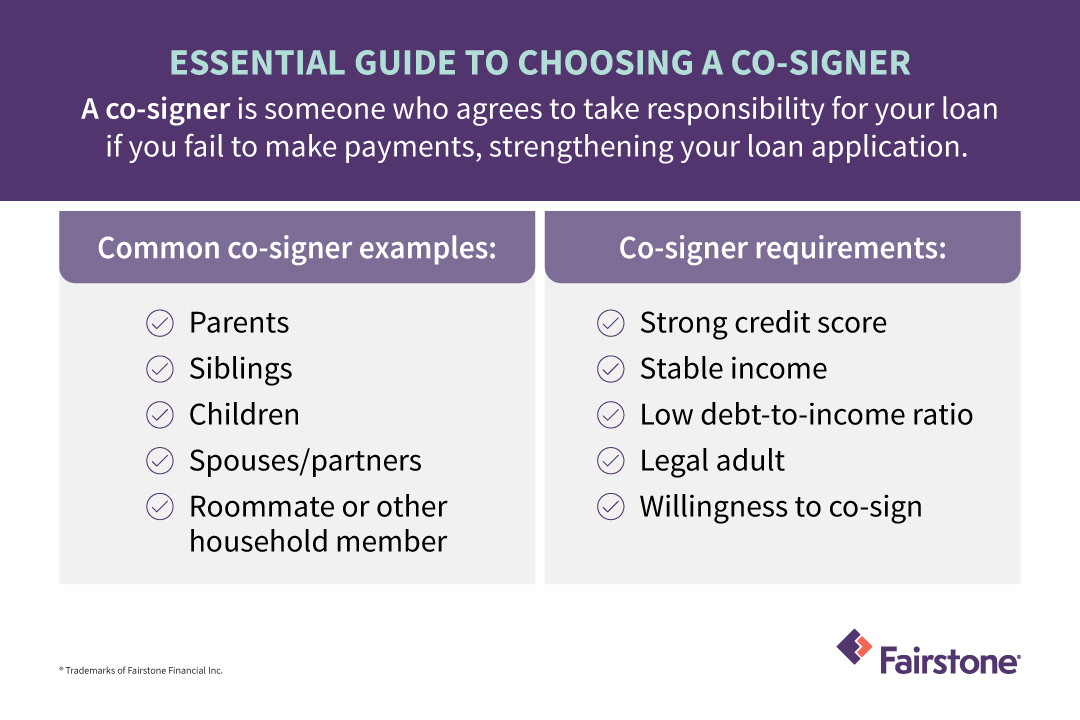 Does Being A Co Signer Affect Your Credit | Detroit Chinatown
So, what steps can you take to protect yourself while still helping someone you care about? First, check the borrower's credit history before agreeing to sign anything. Second, set up payment alerts so you're notified immediately if a payment is missed. Third, establish a clear agreement with the borrower outlining expectations and responsibilities. Finally, consider only cosigning for amounts and relationships that feel manageable. It's wise to limit your exposure by avoiding cosigning multiple large loans at the same time, as the cumulative impact on your credit can be substantial and difficult to recover from quickly.
In the end, being a cosigner is a powerful act of trust and generosity. It can open doors for people who might otherwise not have access to important financial milestones. However, as we've seen, it carries real and sometimes lasting consequences for your own credit profile. By staying informed, setting boundaries, and keeping open communication with the borrower, you can balance helping others while safeguarding your financial future. Cosigning doesn't have to be risky — it just requires smart decisions and a little caution.