Buying An Annuity With Cash
So, you’ve got a giant pile of cash. Maybe you sold a house, inherited your eccentric uncle’s coin collection, or finally got that settlement from the “Worst Hot Tub Experienc...

So, you’ve got a giant pile of cash. Maybe you sold a house, inherited your eccentric uncle’s coin collection, or finally got that settlement from the “Worst Hot Tub Experience of 2004.” Now what? You could buy twelve golden retriever puppies, but let me suggest something truly wild: buying an annuity with cash. It sounds like something your accountant would whisper about at a dull party, but stick with me—this is funnier than you think.
The Great Cash Dilemma
Picture this: you’re sitting on a mountain of cash like a dragon in a Skyrim meme. You could buy a solid gold toilet (yes, someone did that) or you could hand that cash to an insurance company in exchange for a steady income stream. Exciting, right? It’s like paying a stranger to give you your own money back, but spread out over time—like a reverse lottery where you’re guaranteed to win slowly. The surprising fact? Over 40% of Americans would rather eat a ghost pepper than think about annuities, but the industry handles trillions of dollars every year. So someone’s doing it.
What Is This Sorcery?
An annuity is basically a contract with an insurance company. You hand them a bag of cash (treasure chest optional) and they promise to send you checks for the rest of your life or a set number of years. It’s like buying a personal pension that doesn’t require you to wear a suit and retire to Florida. The catch? You’re betting you’ll live long enough to get your money back. Plot twist: annuities have been around since ancient Rome, where gladiators used them to fund retirement. True story—Caesar probably didn’t die for that, but you get the idea.
Must Read
The “Buying With Cash” Part
Here’s where it gets silly. Most people buy annuities with 401(k) money, not a duffel bag of twenties. But paying cash means you dodge a ton of tax headaches. It’s like sneaking into a movie theater without paying for popcorn—except the popcorn is your life savings, and the theater is the IRS. Cash is king here because you avoid the “taxable rollover” jazz that makes your hair fall out. Plus, you get a fixed rate that’s often higher than a savings account. Your bank is paying you 0.01% interest? An annuity might hand you 4–5%, which is enough to buy 23 extra wheelbarrows for your cash.
The Fun, Weird Fine Print
You can’t just pour cash into an annuity and forget it. There are surrender periods where you can’t touch the money for 5–10 years without paying a penalty—like a gym membership, but for your retirement. Don’t buy an annuity if you might need that cash next Tuesday for a boat. On the flipside, some annuities offer “guaranteed lifetime income,” which means if you live to 127, the insurance company is legally obligated to keep paying you. That’s right—you can outlast the company’s entire actuarial department. Villainous laughter optional.
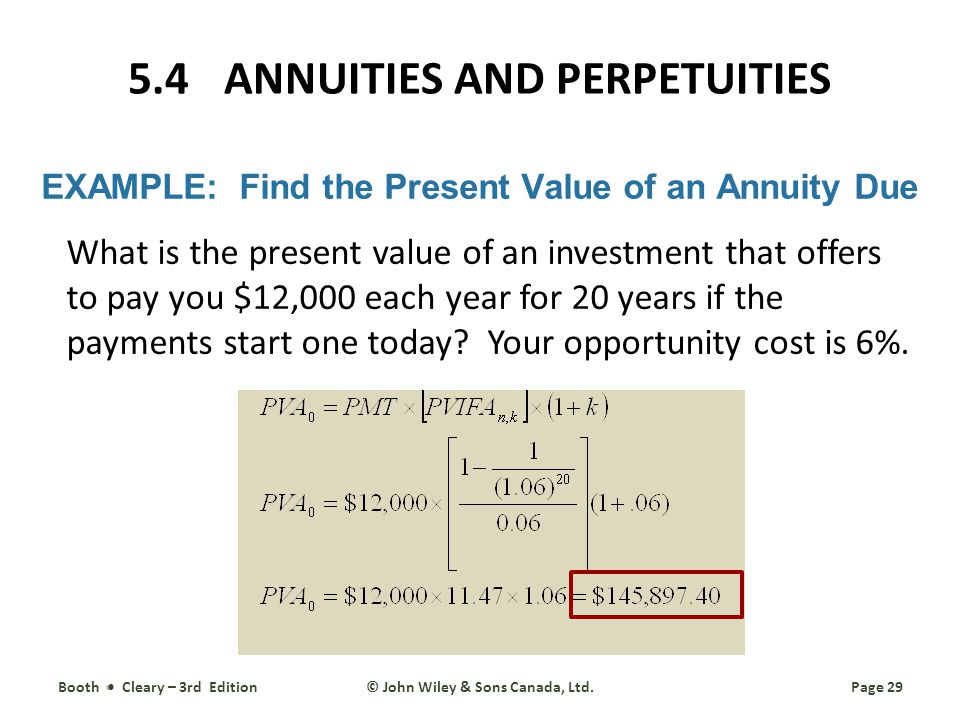 How do I know if buying an annuity is right for me? | Simple-Accounting.org
But Wait, There’s More!
Here’s a surprising fact: annuities can be deathly boring or unexpectedly dramatic. Some have inflation riders that adjust payments when the price of avocado toast skyrockets. Others have “death benefits” where your heirs get the leftover cash if you kick the bucket early. It’s like setting up a trust fund for your cat—if Fluffy survives you. Pro tip: read the contract carefully. Insurance companies once used invisible ink and legalese invented by mimes. Today, they’re better, but still—if a sentence has more commas than a Hemingway novel, ask questions.
Should You Do It?
If you have cash burning a hole in your pocket and want a guaranteed income stream that’s as exciting as watching paint dry, buying an annuity with cash might be your jam. It’s not sexy. It won’t make you the life of a cocktail party. But it will let you sleep at night knowing you can afford Netflix and denture cream until you’re 99. One study found that people with annuities report higher life satisfaction than those who wing it with stock tips from their barber. So maybe the boring path is actually the punchline.
The Final, Uncomfortable Truth
Remember: buying an annuity with cash is a commitment. You’re locking away a pile of money in exchange for peace of mind. And peace of mind—especially in today’s economy—is like finding a unicorn. It’s rare, magical, and might leave you broke if you try to sell it. But if you’re the kind of person who enjoys knowing exactly where your next $500 is coming from for the next 30 years? Go for it. Just don’t buy the luxury annuity that comes with a personal butler. I checked—they don’t exist. Yet.
